Sweat Equity vs Cash Contribution: How Partners Can Stay Fair
Compare sweat equity and cash contributions in business partnerships—how to value unpaid work, balance risk, and document fair ownership splits.
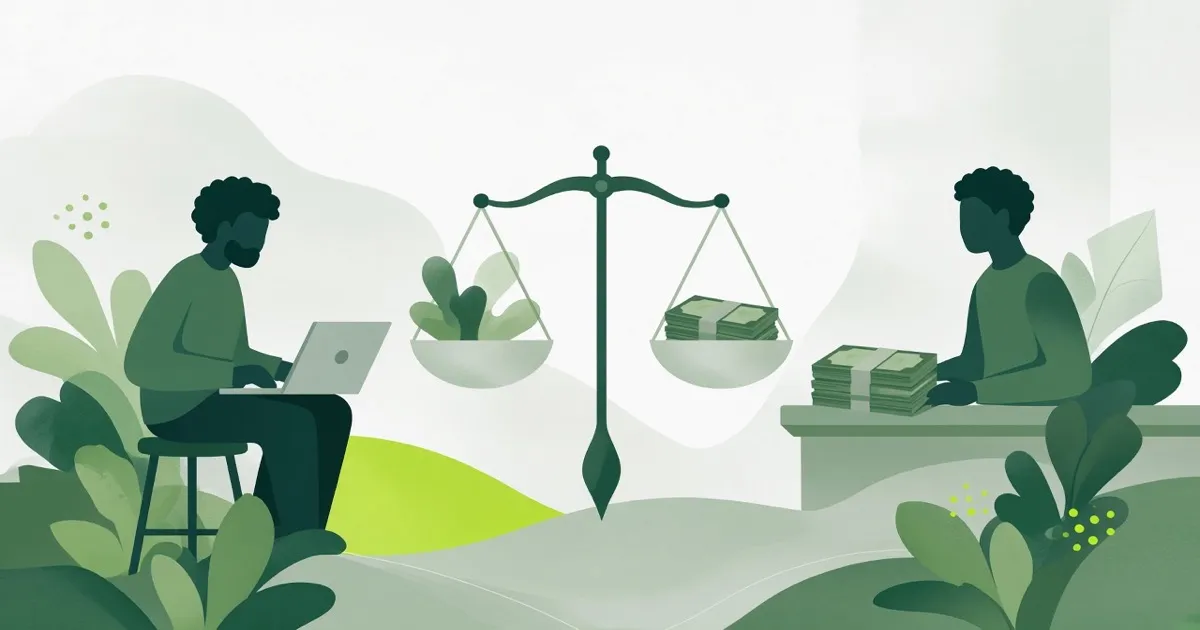
In many startups and side businesses, one partner writes checks while the other writes code, serves clients, builds the brand, or runs operations without a paycheck. That unpaid labor is often called sweat equity. The cash partner may ask: “Why should time count like money?” The time partner may ask: “Why should my months of work count less than your one transfer?”
Neither question is petty. Cash and sweat equity carry different risks, timing, and tax implications. Fair partnerships name how each counts before revenue arrives—not after one side feels exploited.
This article explains sweat equity vs cash contribution, common valuation approaches, pitfalls, and documentation habits. Examples use round numbers for teaching; your fair split depends on your agreement and professional advice.
Disclaimer: Sweat equity and ownership allocations can have legal and tax consequences. This article is educational only. Consult attorneys and tax advisors before treating labor as equity or issuing ownership interests.
Definitions: cash contribution vs sweat equity
| Concept | What it usually means | When it is recognized |
|---|---|---|
| Cash contribution | Money or purchased assets transferred to the business | At funding date (bank statement) |
| Sweat equity | Unpaid or below-market labor contributed for ownership | Over time, per agreed schedule or milestone |
| Paid labor | Salary, contractor fees, or draws for work | When paid; may reduce need for sweat equity |
Sweat equity is not “free work because we are friends.” It is deferred compensation exchanged for ownership, usually documented.
Why the comparison gets emotional
Cash contributors often feel tangible risk: money left their account and cannot be recalled easily. Sweat contributors feel opportunity cost: they could have billed clients elsewhere or taken a salaried job.
Both views are valid. Problems arise when:
- Sweat is assumed but never quantified
- Cash is treated as the only “real” investment
- Ownership is fifty-fifty while inputs are wildly uneven
- One partner reduces hours without revisiting equity
Fairness is not always equal splits—it is transparent rules both partners accepted in writing.
Common frameworks for balancing cash and sweat
1. Pro-rata by agreed dollar values
Assign hourly or project rates to labor; add cash contributions; calculate ownership from totals.
Example:
| Partner | Cash | Sweat (200 hrs × $40/hr agreed) | Total valued input |
|---|---|---|---|
| A | $10,000 | $0 | $10,000 |
| B | $0 | $8,000 | $8,000 |
| Total | $18,000 |
Pro-rata ownership ≈ 55.6% A / 44.4% B before negotiation.
Use the Partnership Contribution Calculator to model cash plus valued labor side by side.
2. Milestone-based equity earn-in
Sweat equity vests when deliverables happen: MVP launched, first ten paying customers, regulatory approval.
| Milestone | Equity credited to labor partner |
|---|---|
| Brand and site live | 5% |
| Product beta shipped | 10% |
| $5,000 cumulative revenue | 5% additional |
Cash partner may keep higher initial ownership until milestones prove execution.
3. Hybrid: cash buys base; sweat earns upside
Partner A funds $15,000 and holds 60% until Partner B completes agreed hours or milestones; then ownership shifts toward 50/50 or another target.
Document triggers precisely. “When the business succeeds” is not a trigger.
4. Paid work first, sweat equity minimal
Partners pay modest monthly fees for labor at market-ish rates when revenue allows; only residual upside is sweat equity. Reduces ambiguity between salary and ownership.
Valuing sweat equity without fantasy numbers
Sweat equity rates should be defensible, not aspirational CEO salaries on day one.
Practical anchors:
- What would you pay a freelancer for the same task?
- What is the partner’s forgone wage in their local market?
- Is the work full-time or nights-and-weekends?
| Role | Illustrative planning rate (example only) |
|---|---|
| General admin / ops | $25–$40 / hour |
| Skilled trade or specialist | $45–$85 / hour |
| Senior dev or consultant | $75–$150 / hour |
Agree a single planning rate or a small rate card by task type. Revisit annually.
Cash contribution: more than the first wire
Cash partners may also bring:
- Credit guarantees (risk, not always logged)
- Runway for payroll when revenue is zero
- Equipment purchased outright
Track cash and assets in an investment ledger—see how to track partner investments—so sweat equity conversations use the same factual baseline.
For uneven funding patterns, pair this article with the unequal partner investments guide.
Side-by-side risk comparison (honest conversation)
| Risk dimension | Cash contributor | Sweat contributor |
|---|---|---|
| Liquidity loss | Immediate | Delayed (time not billed elsewhere) |
| Recovery if business fails | Often limited | Lost hours; equity may be worthless |
| Visibility | Bank statements | Time logs, deliverables |
| Tax timing | May affect basis now | Complex; advisor required |
Partners who discuss this table openly often land on more balanced earn-in schedules.
Red flags in sweat equity deals
- “You will get equity later” with no formula
- Sweat valued at founder market salary from day one with zero revenue
- Cash partner can dilute or fire sweat partner without buyout terms
- No time logs or deliverable records
- 50/50 split while one side funds 100% of costs
Fix red flags with writing, milestones, and exit clauses—not with optimism.
Documenting sweat equity properly
Minimum documentation:
- Sweat equity agreement summary — rates, hours cap, milestones, vesting
- Time or deliverable log — weekly entries both partners can review
- Investment ledger — cash and asset entries separate from hours
- Ownership schedule — initial % and how it changes when milestones hit
Example time log row:
| Week | Partner | Hours | Tasks | Cumulative hours | Cumulative valued sweat |
|---|---|---|---|---|---|
| W42 | B | 18 | Site build, vendor calls | 92 | $3,680 at $40/hr |
Monthly, compare cumulative sweat to agreed cap. Some deals cap sweat equity at a maximum dollar value to protect cash investors.
When sweat equity should be small or zero
Sweat equity is not mandatory. It fits when:
- Both partners want upside alignment
- Cash is scarce but labor is abundant
- Milestones are measurable
Consider minimal sweat equity when:
- Labor partner already receives market pay
- Business is primarily capital-intensive (inventory, equipment)
- Roles are easily replaceable contractors
Paying fairly for work and keeping ownership simpler is often cleaner than heroic sweat models.
Tax and legal nuances (high level)
Tax treatment of sweat equity varies widely. Issuing ownership for services may create taxable income for the recipient in some jurisdictions. Cash contributors may have different basis rules.
Do not rely on blog summaries for filing positions. Bring your documented rates and agreements to a qualified tax professional early—especially before year-end.
Negotiation tips that preserve relationships
- Use third-party benchmarks (freelance rates, industry salary bands) to depersonalize numbers
- Model three scenarios: conservative, base, optimistic revenue
- Agree what happens if sweat partner takes a full-time job elsewhere
- Set a review date six months after launch
Worked example: café pop-up partnership
Partner A contributes $6,000 for equipment and initial ingredients. Partner B contributes 120 hours over three months at agreed $35/hr ($4,200 valued sweat) plus recipe IP valued at $800 in writing.
| Input | Amount |
|---|---|
| A cash | $6,000 |
| B sweat + IP | $5,000 |
| Total | $11,000 |
| Pro-rata | ~54.5% A / 45.5% B |
They negotiate 55/45 ownership, cap B’s additional sweat at 200 hours unless both agree, and log expenses separately in shared tracking.
Connecting sweat equity to profit and exit
Ownership from sweat equity typically affects profit share and exit proceeds, not automatic extra salary. On exit:
- Buyout formulas should reference ownership % and possibly unvested sweat
- Good leaver / bad leaver clauses may adjust sweat equity (lawyer-drafted)
Clarify whether sweat equity vests fully only after a time period (e.g., twelve months of service).
Clawbacks and leaving early
If the sweat partner exits before milestones complete, partners need a written rule:
| Scenario | Possible approach (negotiate with advisors) |
|---|---|
| Leaves after 50% of hours delivered | Retain pro-rata earned equity; forfeit unearned portion |
| Leaves due to illness | Good leaver: partial credit per doctor-documented inability |
| Cash partner stops funding | Sweat partner may pause vesting until funding resumes |
| Mutual shutdown | Liquidate assets; distribute per ownership after debts |
“Fair” means different things to different people. Predictable matters more than perfect.
Comparing three ownership outcomes (same inputs)
Using the café pop-up example earlier ($6,000 cash vs $5,000 valued sweat):
| Model | Partner A | Partner B | Comment |
|---|---|---|---|
| Pure pro-rata on valued inputs | 54.5% | 45.5% | Math-only |
| Negotiated split | 55% | 45% | Small adjustment for IP |
| 50/50 without documentation | 50% | 50% | Easy now; fragile later if B reduces hours |
The third row is a common friendship default. It works until someone feels the split no longer matches reality.
Sweat equity and outside investors
If you may raise funds later, sweat equity history matters. Investors often ask:
- Who earned what ownership and on what basis?
- Are all founders on vesting schedules?
- Is any equity subject to dispute?
Messy sweat logs delay deals or force painful renegotiation. Clean logs signal you can govern the company.
Practical weekly ritual for sweat-heavy partnerships
- Monday: Agree top three deliverables for the sweat partner
- Friday: Log hours and outputs; cash partner reviews in ten minutes
- Month-end: Update cumulative sweat value vs. cap; compare to partnership contribution calculator scenarios
Rituals beat annual surprises.
FAQs
Is sweat equity the same as profit share?
Not necessarily. Sweat equity usually means ownership earned through labor. Profit share follows ownership unless you structure differently with advisors.
What if the sweat partner works fewer hours than promised?
Your agreement should say whether unearned equity is forfeited, renegotiated, or bought back.
Can cash partners also earn sweat equity?
Yes. Many founders both fund and work. Log each type separately.
Should we use fair market value for all hours?
Use planning rates you both accept, documented at the start. FMV debates belong in that initial negotiation.
How does this relate to 50/50 partnerships?
Equal ownership can work when valued inputs are equal over time. When cash and hours are uneven, equal splits without documentation often break.
Takeaways
Sweat equity vs cash contribution is a balancing act between liquidity risk and time risk. Fair partnerships assign planning rates or milestones, cap sweat where needed, log hours and cash separately, and align ownership with documented inputs—not with friendship defaults alone.
Explore Taqsim App to keep contributions, expenses, and partnership context clear as cash and labor both flow into your business.
Managing money with a business partner?
Keep shared expenses, investments, and profits organized with Taqsim App.